
Self-Employed Funding & Cash Advances
Self-employed and need capital without a W-2? Giggle Finance approves on the money that actually lands in your account, not on a credit score or two years of tax returns. Most applicants get a decision in about five minutes and funding up to $15,000 the same day, with a soft credit check only.
This page covers who qualifies, how a self-employed cash advance works, what it costs, and when it is the right tool rather than the wrong one.
Looking for a “self-employed loan”?
That is the phrase most people search, so here is the distinction that matters. A Giggle advance is not a loan. Giggle purchases a small portion of your future business earnings and gives you the cash now, and repayment comes out of what you earn going forward.
That structure is exactly why it works when bank lending does not. There is no minimum credit score, no fixed monthly bill that ignores a slow month, and no collateral. If you have been self-employed for at least three months and average $1,500 a month in deposits, you can see an offer without affecting your credit.
Check your offer in about five minutes →
Financing for Self-Employed Professionals
There are many wonderful benefits of being self-employed—leaving the 9-5, following your passion, becoming your own boss, and choosing when you work. But, like other small business owners, access to financing for self-employed professionals can be challenging.
Lenders often look for consistency and stability in income from loan applicants, and this can work against most self-employed professionals with inherently unpredictable revenue streams. Additionally, documentation requirements are stringent and directed toward W-2 workers who receive regular and consistent income every two weeks. As a result, lending institutions are hesitant to lend money to small businesses and freelancers.
At Giggle Finance, we believe that self-employed professionals deserve fast and transparent financing. It’s easy to apply and only takes a matter of seconds. Today, self-employed professionals have only a few options, such as predatory Payday Loans and self-employed loans. However, with a Giggle Business Advance, the cash is tailored to suit your needs, whether you’ll use it for renovations, debt consolidation, or additional capital.
What We Do
Giggle Finance is an online finance platform dedicated to helping self-employed professionals and small business owners quickly access capital when they need it.
We Help Build Your Financial Future
Our goal is to help build your financial standing without affecting your credit score. Unlike a self-employed loan with fixed payment terms, the funds from a Giggle Business Advance provide greater payment flexibility so your business can continue moving forward.
If you work with us, you’ll join other self-employed professionals and small business owners who access instant and affordable funding whenever they need it.
How a Giggle Business Advance Works
A Giggle Business Advance allows self-employed professionals to access working capital by selling a percentage of their future sales. You’ll receive the funds in minutes and repay the advance through automated debits, plus a small service fee until paid in full.
We don’t have a minimum credit requirement. Instead, we look at your bank statements and other financial documents to determine how much you can afford. We require at least three months in business to qualify for an advance, making it a perfect option for newly self-employed professionals.
Have some questions about our process? Check out our Frequently Asked Questions here.
Why Choose Giggle Finance
We’re here to revolutionize small business funding through the latest technology, exceptional customer service, and transparency.
1. Immediate Approval
Instant application approvals so you can review your terms and know how much you qualify for in minutes.
2. Instant Cash
We’ll wire the money into your bank account within minutes. You can immediately use the funds for any pressing business needs.
3. Simple Application Process
It takes less than eight minutes to fill out our fully-automated application and get funded.
4. Funding Up To $15,000
Self-employed loans typically cap at $2,500, with Giggle Finance you can qualify for a business advance for up to $15,000.
5. No Credit Requirements
We don’t have any credit score or history requirements. Bankruptcy, medical bills, or foreclosures? All NO problem!
6. No Hidden Fees
We believe that transparency and integrity build trust, so we make sure that our application process and contracts are easy to understand, with no hidden fees.
7. Flexible Payment Schedule
Payments are automatically debited from your account until the advance is paid in full.
8. Fully Secure
We value your privacy, so we made sure Giggle operates using 256-bit encryption. This means that your personal information and passwords are never viewed, displayed, or stored.
A Giggle Finance Application is as Easy as 1, 2, 3!
We know that self-employed professionals have a lot on their plate; that’s why we want to keep our application process as simple as possible.
Our online application process only takes less than 8 minutes to complete. Tell us a few details about your business and securely connect your bank account. Approval is instant, and you’ll receive the amount you’ve qualified for in minutes.
Step 1: Complete the online application
We’ll ask for basic information about your business and your banking details.
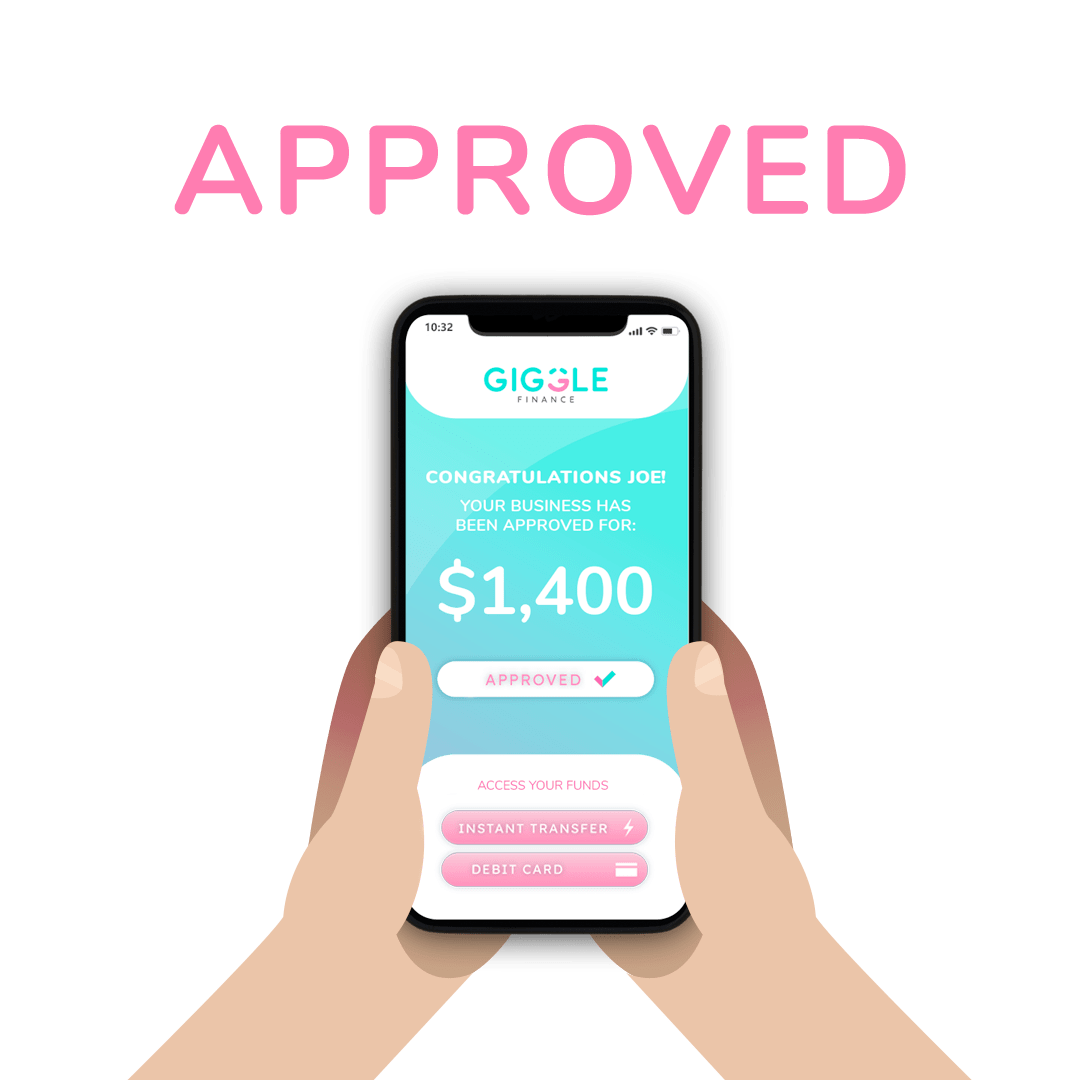
Step 2: Approval
You’ll know the status of your application immediately. We’ll send you details regarding rates, terms, and how much you qualify for.
Step 3: Get funded
Once approved, we’ll make an electronic fund transfer to deposit the money into your account immediately. You can instantly access your funds and use the money as you deem fit for your business– for additional capital, inventory, hiring – it’s all up to you.
How to Use the Funds from a Giggle Business Advance
Here are some of the most common ways self-employed professionals use the funds from the Giggle Advance:
1. Marketing and Advertising
Investing in marketing is a necessary expense for self-employed professionals who want to grow and expand their operations. Effective marketing can help attract new customers, keep existing ones, improve brand visibility, and generate a higher return on investment (ROI).
With a Giggle Business Advance, you’ll have the financial resources needed to invest in marketing software, hiring new staff, or the services of a marketing agency.
2. Investing in Your Employees
The people who work for you are your most valuable assets, so it makes sense to invest in their personal and professional development. You can do so by offering perks and benefits tailored to their needs and preferences. For example, if you’re in the trucking business and your employees are going above and beyond their work, you can give them additional benefits or overtime pay with a truck driver advance. Giggle Finance opens more opportunities for your employees to feel secure and valued.
3. Inventory
You can use the advance to replenish inventory that’s running low or take advantage of a bulk discount deal. An updated inventory opens your business to new markets and attracts more people.
4. Additional Working Capital
Additional working capital is one of the main reasons why self-employed professionals apply for a Giggle Business Advance. Inconsistent revenue streams and seasonal sales fluctuations can put a dent in your cash flow. The funds from Giggle help you to bridge cash flow gaps so you can continue running your business.
5. Pay Off Higher-Cost Financing
Taking out an advance to pay for another loan may seem odd, but debt refinancing is also a common reason to apply for a Giggle Business Advance. It’s an excellent option for self-employed professionals to use funds to pay off their debts and have extra cash for other necessities.
6. Expand Your Products and Services
Expanding your products and service lines can increase your revenue and help you stay competitive with your peers. A Giggle Business Advance allows you to make the necessary investments to keep your business relevant. Whether you need a 500-dollar advance or 5,000-dollar additional cash, you can get them at Giggle Finance.

Running a business rather than a side hustle? See small business funding up to $15,000, approved on your deposits.
Disclaimer: Giggle provides Revenue Based Financing programs that are for business purposes only. Any mention of any loan product(s), consumer product(s) or other forms of financing are solely for marketing and educational content purposes and to help distinguish Giggle’s product from other comparable financing options available in the market.
What Is a Self-Employed Cash Advance?
A self-employed cash advance is a fast, flexible way to access money you’ve already earned but haven’t yet received. Whether your income comes from client projects, gig platforms, or business sales, a cash advance helps you tap into that incoming revenue without waiting for it to clear your account.
You’re not borrowing based on credit history or making a long-term commitment. Instead, a portion of your future earnings is advanced to you now, giving you immediate cash flow when you need it most, like covering time-sensitive expenses, smoothing out irregular income, or taking on new opportunities.
This type of funding works best for self-employed workers who want control over their timing. It bridges the gap between when you earn and when you actually get paid, without locking you into a traditional repayment model.
With platforms like Giggle Finance, the process is simple, fast, and aligned with how independent workers operate day to day.
How It Differs from a Traditional Loan
A self-employed cash advance isn’t a loan, and that’s actually a good thing. Traditional loans often involve detailed applications, hard credit checks, and fixed payment plans that don’t reflect how freelancers or business owners really earn.
A Giggle Advance works differently. It’s based on your future earnings, so if your income shifts, your repayments adjust too. There’s also only a soft credit pull, meaning your credit score won’t be affected just for applying.
This flexibility is especially helpful for freelance designers, Etsy sellers, rideshare drivers, and landscapers whose income isn’t always predictable.
Built for Today’s Self-Employed Workforce
More people are working outside of the 9-to-5, yet most financial institutions still expect W-2s, fixed salaries, and long credit histories. That disconnect leaves many self-employed professionals shut out of the funding they deserve.
Giggle Finance was built with gig workers, freelancers, and small business owners in mind. The process is 100% online, available 24/7, and doesn’t require documents you may not have. Your recent income activity is enough.
Want to explore more ways to grow your income and stay financially prepared? Check out this guide to financial strategies for the self-employed—you might be surprised by how many tools are out there to help you grow your income.
Why Traditional Loans Don’t Work for the Self-Employed
If you’re self-employed, you already know that earning money outside a traditional job gives you flexibility. Still, it also comes with challenges, especially when it’s time to apply for funding.
Unfortunately, most traditional lenders still use outdated standards built for full-time employees with steady W-2 paychecks. That makes it harder for freelancers, gig workers, and small business owners to get approved even when earning consistently.
Here’s why the system doesn’t work in your favor:
Banks Want Proof of Steady, Predictable Income
Traditional lenders expect regular pay stubs or W-2s from an employer. But self-employed income doesn’t look like that. You might earn from multiple sources, your income may fluctuate, and you probably don’t get paid on a fixed schedule.
Even if you’re making good money overall, lenders often see irregular income as risky and reject your application because it doesn’t fit their mold.
The Application Process Is Built for Employees
To apply for a loan, you’re usually asked to submit:
- Two years of tax returns
- Business licenses or registrations
- Profit and loss statements
- Long credit histories
- Employer contact information
For many self-employed people, this is time-consuming and often not relevant. Even if you provide everything they ask for, it still might not be enough to get approved.
Credit Scores Carry Too Much Weight
If your credit score isn’t perfect, traditional lenders may turn you away, regardless of your current earnings. Even applying can hurt your score since most banks run a hard credit check upfront.
That’s a big risk for self-employed workers who may build their credit or recover from income dips during slow seasons.
The System Wasn’t Built for the Way You Work
Today’s workforce is changing fast. Millions of Americans now earn income through freelancing, gig work, online sales, and side businesses. However, most banks still use a one-size-fits-all approach that excludes anyone who doesn’t fit into the 9-to-5 model.
That gap leaves self-employed workers underserved and overlooked. They are forced to rely on high-interest credit cards, payday loans, or personal savings to stay afloat.
With Giggle, that gap closes. You get access to a self-employed cash advance that understands how you work. It’s fast, fair, and built for your reality, not a system from 20 years ago.
Need fast access to funds without jumping through hoops? You’re in the right place. Let’s explore how the process works next.
When a Cash Advance Makes Sense
Even when business is going well, financial gaps can pop up—unexpected expenses, slow-paying clients, or seasonal dips in demand. For self-employed workers, these moments can create real stress, especially when time is tight and traditional funding isn’t realistic.
A self-employed cash advance can be a practical solution. It’s fast, flexible, and built around how you earn. Below are a few real-life scenarios where this type of funding helps you stay focused, not stretched thin.
Covering Bills Between Clients
Freelance work isn’t always steady. One month you’re fully booked, the next you’re chasing unpaid invoices or waiting for a new project to kick off.
Let’s say you’re a freelance graphic designer, and a few clients hit pause at the same time. Suddenly, rent and utilities are due, but payments aren’t coming in. Instead of relying on credit cards or borrowing from friends, a self-employed cash advance gives you the breathing room to stay current on bills while you line up your next job.
Replacing or Upgrading Equipment
Your gear keeps your business running. When something breaks or needs an upgrade, you don’t always have time to wait for your next payout.
For example, a photographer drops a lens days before a scheduled shoot. Replacing it quickly is the only way to keep the job and the income. A cash advance makes that possible, so your business doesn’t skip a beat.
Handling Tax Payments or IRS Surprises
Tax season doesn’t always go as planned. Maybe your income was higher than expected or a quarterly payment slipped through the cracks.
Imagine realizing you owe more than you budgeted for right before the tax deadline. Instead of pulling from savings or scrambling for a traditional loan, a cash advance helps you cover the payment with less stress and fewer delays.
Want to avoid surprises next year? Check out our Easy guide to tax credits for the self-employed for tips on saving more while managing your tax responsibilities.
Building a Buffer During Slower Seasons
Most self-employed businesses have slower months. Even when income dips, fixed costs like rent, insurance, or subscriptions keep coming.
Take Jordan, who runs a small event rental business. During winter, bookings dropped, but his warehouse rent didn’t. Using a cash advance, he covered his fixed costs while waiting for spring events to ramp back up. That kind of flexibility isn’t always possible with traditional self-employment loans that require a full credit check, lengthy review, and steady W-2 income.
The 1099 Income Problem That Banks Still Haven’t Solved
If you earn 1099 income, you already know what it’s like to be turned away by a bank that wants a W-2. Even if you’re earning consistently, that often isn’t enough for a traditional bank. To a traditional lender, irregular deposits, multiple income streams, and no employer on record all look like risk. That’s the core of the problem for freelancers, rideshare drivers, independent contractors, and anyone else operating outside a salaried job.
Why 1099 Workers Are Underserved by Traditional Lenders
Most freelancers still encounter the same friction when they need funding. Lenders want two years of tax returns, proof of stable employment, and a credit score that reflects steady borrowing, not the reality of 1099 income that peaks in some months and dips in others. As a result, even a strong quarter doesn’t help if the lender focuses only on your weakest month.
What Actually Reflects Your Earning Ability
Your bank account tells a more honest story than your tax return. If client payments, platform payouts, and sales deposits are arriving regularly, they provide a much clearer picture of your earning ability than a single tax document ever could.
A cash advance for self-employed workers is built around that very idea. Instead of pulling a credit report and asking for employer details, it looks at your deposit activity over the past few months and makes a funding decision based on what you actually earn today.
Tips to Manage Your Cash Advance Like a Pro
Getting a self-employed cash advance is a great move when you need fast funding, but how you manage that money can make a big difference. Here are a few smart strategies to help you stretch every dollar and stay in control.
1. Know What It’s For
Before you accept the funds, be clear about what you need them for. Are you covering rent while waiting on client payments? Replacing broken equipment? Investing in marketing? Having a plan helps you avoid unnecessary spending and keeps your goals in focus.
2. Budget with Your Gig Flow in Mind
Gig work doesn’t come with a steady paycheck, so your budget shouldn’t be built around your busiest week. Instead, look at what you typically earn over time, then use that number to shape your monthly spending.
Planning around your average income helps you stay consistent, even when things slow down. Apps like EveryDollar, YNAB, or even a simple spreadsheet can make it easier to track what’s coming in, what’s going out, and what you can safely set aside.
3. Prioritize Business-Boosting Costs
If you can, use your advance to fund something that will help your business grow. Maybe it’s restocking supplies, running a quick ad campaign, or paying for a productivity tool. Spending money on income-generating tasks makes it easier to repay the advance without strain.
4. Set Aside for Taxes
It’s easy to forget about quarterly tax payments until they’re knocking at your door. If you received a cash advance and know some of it will support business income, go ahead and tuck away a portion for taxes. It’s a small step that prevents big headaches. If you need help with that, you can check out this easy tax guide for self-employed workers.
5. Use Digital Tools to Stay Organized
There’s no need to track everything by hand. Use mobile apps like QuickBooks Self-Employed, Wave, or Expensify to manage receipts, categorize expenses, and even estimate your taxes. Keeping tabs on your financial habits can help you make better decisions moving forward.
6. Don’t Take More Than You Need
Qualifying for a cash advance is simple, but being approved for a higher amount doesn’t mean you should take it all. The smartest move? Only borrow what you need to cover your current expenses or keep your business moving.
This keeps your repayment manageable and your goals on track. Clear, focused funding decisions help you grow sustainably without additional pressure later.
Want more ways to stay financially strong? Check out this guide on financial strategies for the self-employed to keep your income flowing year-round.
Frequently asked questions
Can I qualify without a W-2 or tax returns?
Yes. You connect the bank account where your client payments or platform payouts land, and Giggle reads your deposit history directly. No tax returns, W-2s, pay stubs or employment letters.
Is there a minimum credit score?
No. Checking your eligibility uses a soft pull that does not affect your score, and there is no minimum FICO requirement. Consistent deposits are what matter.
How much can I get?
New customers can qualify for up to $15,000 and returning customers in good standing up to $20,000, based on how much you earn and how steady your income is.
How fast is funding?
A decision in about five minutes, with funds typically arriving the same day after you accept. Applications are processed 24/7.
What can I use it for?
Business purposes: equipment, inventory, marketing, working capital, tax bills, covering a slow season, or bridging the gap on a net-30 invoice.
What happens in a slow month?
Repayment is a percentage of your revenue, so a slower period means a smaller payment. You can also pay ahead on strong weeks, and advances repaid within 30 days qualify for an early-repayment discount.
Get funded as a self-employed professional
If you have three months of self-employed income and average $1,500 a month in deposits, see what you qualify for. It takes about five minutes and will not affect your credit.
Funding by profession
Giggle Finance works with gig workers across every platform. Find the guide that matches how you earn:
- Cash advance for gig workers
- Bad credit funding
- Uber & Lyft drivers
- DoorDash & delivery drivers
- Amazon workers & Flex drivers
- Gig apps that pay same day
Disclaimer: Giggle Finance provides Revenue-Based Financing programs for business purposes only. Any mention of any loan product(s), consumer product(s), or other forms of financing is solely for marketing and educational content purposes and to help distinguish Giggle Finance’s product from other comparable financing options available in the market.